Diwali is on November 8 this year, and the week before the festive rush began, the Reserve Bank of India changed the price of money. On October 7, the Monetary Policy Committee raised the repo rate by 25 basis points to 5.50% — the first increase since 2023 — and shifted its stance from neutral to calibrated tightening, with the statement making clear that rate cuts are off the table in the near term. By October 8, Punjab National Bank, Bank of Baroda, Indian Bank and several others had raised their repo-linked lending rates by the same quarter point. If you rent a home, pay an EMI, or are planning to buy gold, a phone or a two-wheeler this month, that decision reaches your wallet. Here is what actually changes, and what to do about it before the festive spending starts.
What the RBI did, in one minute
- Repo rate: 5.25% → 5.50%. The standing deposit facility moved to 5.25% and the marginal standing facility and Bank Rate to 5.75%.
- Stance: neutral → calibrated tightening. Four of six members backed the shift; the vote on the rate itself was 6–0.
- Why: inflation has climbed for months (CPI 4.82% in August, food near 6%), Brent crude is around $101 a barrel — more than 50% higher than a year ago — and the rupee has been under pressure.
- What the RBI expects next: FY27 inflation at 5.2%, with a peak of around 6.0% in the October–December quarter — in other words, right now. Growth is still projected at a strong 7.1%.
- Next decision: December 4. Minutes of this meeting come out on October 21 and will show how hawkish the committee really is.
A quarter point sounds small. The reason it matters is the direction: after 125 basis points of cuts in 2025, the cycle has turned, and the RBI has told borrowers not to expect relief soon. Plan for rates to stay here or go higher through the winter.
If you have a home loan: the exact numbers
Most floating-rate home loans taken since 2019 are linked to the repo rate and reset at least once a quarter, so the 25-point increase shows up at your next reset, not instantly. On a ₹40 lakh balance with 18 years left, moving from 8.50% to 8.75% lifts the EMI from about ₹36,218 to about ₹36,836 — roughly ₹620 a month, or about ₹1.3 lakh in extra interest over the remaining tenure. If your bank keeps the EMI unchanged and stretches the tenure instead — the default at many lenders — you pay about nine extra months and roughly ₹3.3 lakh more in interest. That second path feels painless in the festive month and is the more expensive one. Ask your lender which option you have been put on; you can usually choose.
If you rent: three things to watch
- Renewal conversations get firmer: a landlord with a floating-rate loan on your flat just saw their EMI rise. Expect the annual increase to be argued harder. If your lease renews before March, open the discussion now and offer a longer lock-in in exchange for a smaller step-up.
- Fewer buyers means more tenants: every time borrowing gets costlier, some first-time buyers postpone and keep renting. More demand for the same flats supports rents in cities that are already tight — Bengaluru, Pune, Gurugram, Hyderabad.
- The deposit is your biggest idle asset: with fixed deposits paying under 6% and the RBI expecting prices to rise faster than that this quarter, two to six months of rent sitting interest-free with a landlord loses value every month. That money is worth more in your emergency fund than in someone else's account.
Gold, gadgets and the festive wishlist
Gold was trading around ₹1.50 lakh per 10 grams on October 7, down from roughly ₹1.59 lakh in August but still far above last Diwali. Dhanteras buying is a tradition, not an obligation: a small coin or digital gold keeps the ritual without the lump sum. Smartphones and appliances are the other big-ticket categories, and this is where the rate hike quietly bites — consumer-durable EMIs and buy-now-pay-later schemes are priced off the same rising cost of funds, and the zero-cost EMI on the sticker often hides a processing fee or a discount you forgo. Read the Key Facts Statement on any festive loan: the APR, not the headline rate, is the price.
A festive budget that survives December
- Fixed bills first: rent, EMIs, school fees and insurance for November and December come out of the plan before a single gift. The festive month is the month lenders watch most closely for missed payments.
- Set a number, in writing: decide the total festive spend before the sales start, split it by category (clothes, gifts, travel, home) and track it against the number weekly.
- Cash for consumption, credit only for assets: borrow for a laptop you need for work if you must; never for a holiday or a gift. A 36% p.a. credit-card balance carried into January is the most expensive Diwali decoration there is.
- Leave the emergency fund alone: dipping into savings to fund the season is common — and dangerous in a year when the RBI itself expects inflation to peak this quarter and household debt is already high.
- Pay EMIs by auto-debit and keep the balance there two days early: a bounced NACH in the festive season costs a bank charge, a bounce fee from the lender and a mark on your credit report, for no good reason.
- Rate-shop before you extend: if you are stretching a home loan, personal loan or deposit loan this month, compare APRs across lenders — the quarter-point hike has not been passed on uniformly.
Moving homes this season? Don't lock up the money
October and November are peak moving months — new jobs after appraisal season, families shifting before the school year, couples setting up a first home. It is also, after this week, the worst time to hand over a large security deposit. On RentHatke, an RBI-registered lending partner pays the landlord the deposit so you move in without the lump sum, and you repay it in small monthly instalments collected by auto-debit on a date you choose. The full cost is set out in a Key Facts Statement before you sign — no surprises after the rate hike — and every on-time instalment builds your credit history. Your savings stay yours for Diwali, for the emergency fund, or simply for a rate cycle that has turned.
Keep your deposit money for Diwali, not for the landlord. Check your zero-deposit eligibility on RentHatke in under 2 minutes — no impact on your credit score. (This article is general information based on the RBI's October 7, 2026 policy statement and bank announcements as of October 8; EMI figures are illustrative and rates vary by lender. It is not financial advice.)
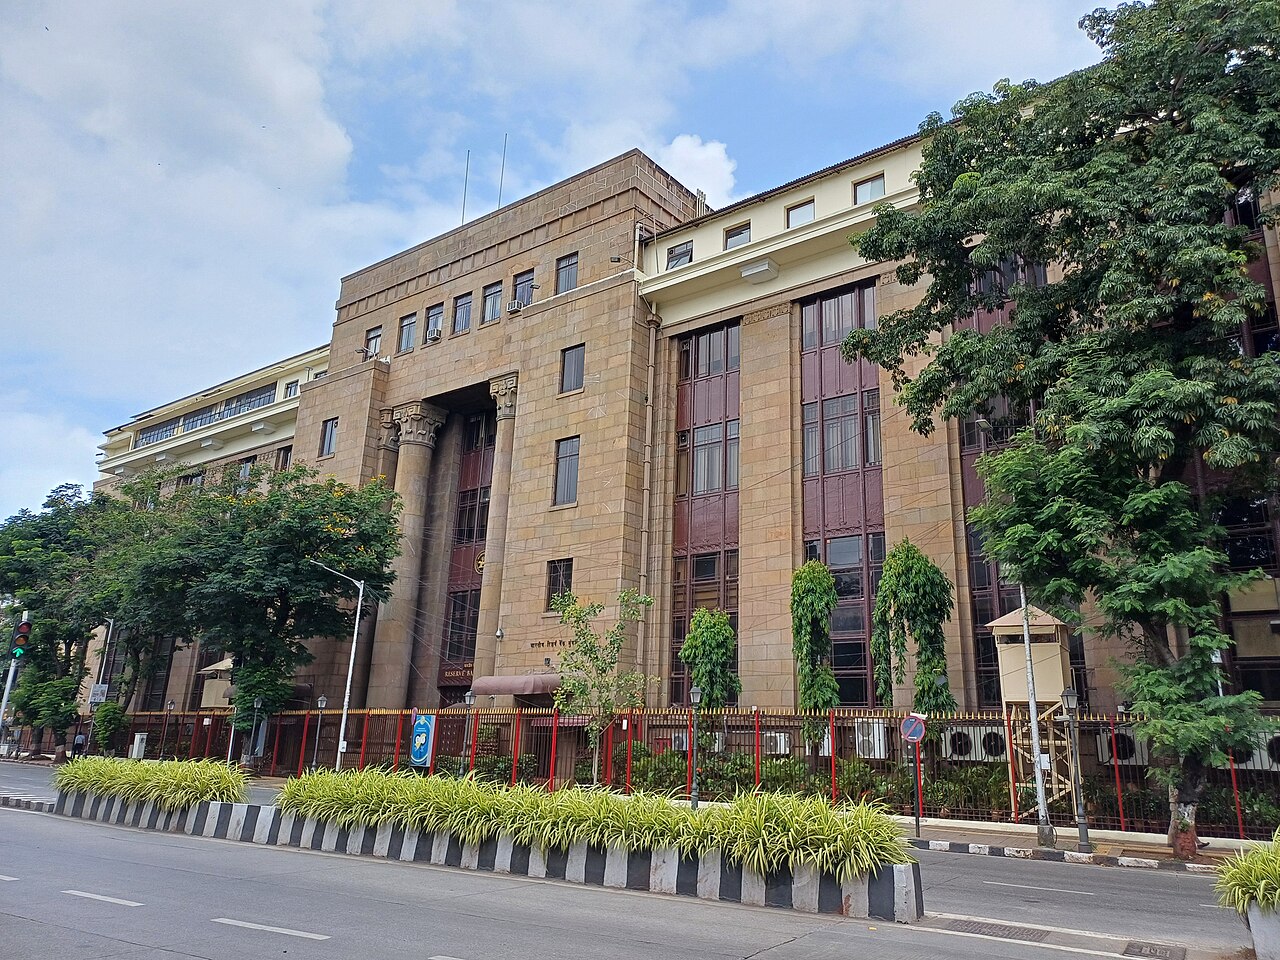
Cover image: Reserve Bank of India headquarters, Mumbai, by DesiBoy101, via Wikimedia Commons (CC BY 4.0).


